
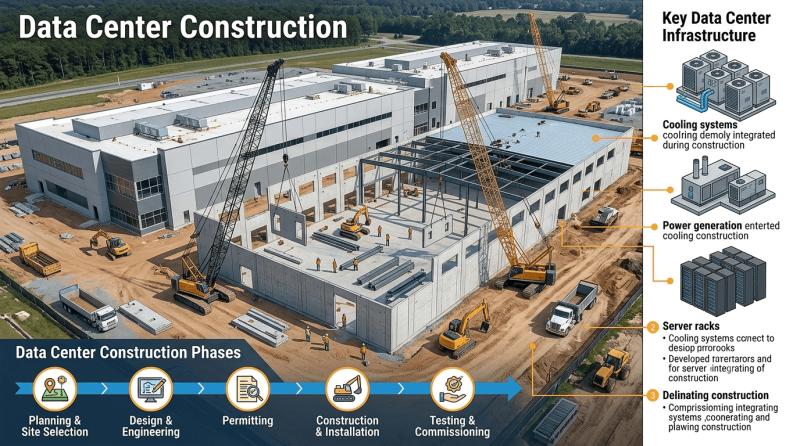
Data Center Construction Market
According to DataM Intelligence, the global data center construction market size was valued at USD 261.31 billion in 2025 and is estimated to reach USD 286.92 billion in 2026, before reaching USD 662.71 billion by 2033, expanding at a CAGR of 9.8% during 2026-2033. The construction pipeline is increasingly being shaped by AI infrastructure, with new facilities requiring different approaches to power capacity, cooling, land use and long-term energy supply.
The nature of data center development is also changing. In 2026, Meta agreed to lease capacity from a new 168 MW AI-enabled data center in Jamnagar, India, while Google moved forward with construction of a planned $15 billion AI hub in Visakhapatnam, Andhra Pradesh. These projects show how hyperscalers and infrastructure partners are developing facilities around AI workloads, renewable energy availability and specialized cooling requirements.
Download Free Sample Report (Get Higher Priority for Corporate Email ID):- https://www.datamintelligence.com/download-sample/data-center-construction-market?indhu
Recent Developments in the Data Center Construction Market
United States
• In September 2026, Aligned Data Centers broke ground on its 2 GW Project Phoenix campus in Pennsylvania, anchoring an estimated US$10 billion regional investment.
• In September 2026, Cushman & Wakefield reported U.S. and Canada data center construction costs rising 21% per MW, driven by supply-chain constraints, labor costs and critical-component expenses.
• In July 2026, the U.S. Department of Energy announced a more than US$100 billion data center campus investment in Kentucky, combining new computing capacity with dedicated energy infrastructure.
Japan
• In August 2026, NTT Data planned to invest at least ¥1.5 trillion to add roughly 750 MW of Japanese data center capacity, targeting 1 GW by 2033.
• In August 2026, Japan’s Development Bank reported 19.7% planned domestic capital-spending growth for FY2026, with AI and data center investments among the key drivers.
• In July 2026, Japan’s Ministry of Internal Affairs and Communications selected FY2026 watt-bit collaboration projects to coordinate electricity, telecommunications and data center infrastructure for rising AI-driven demand.
Mergers and Acquisitions
• TCS/HyperVault – September 2026: HyperVault, a TCS subsidiary, secured 264 acres in Hyderabad to develop a 1 GW AI data center campus, with HyperVault and its partners planning investment of up to ₹70,000 crore (about US$7.4 billion) for phased construction and high-density AI infrastructure.
• CPP Investments, Equinix & atNorth – September 2026: CPP Investments and Equinix completed the acquisition of atNorth, combining its Nordic data-center operating portfolio with a development pipeline across Sweden, Finland, Norway and Denmark to accelerate AI-ready capacity and hyperscale infrastructure expansion. The transaction included a US$4.1 billion financing package supporting the acquisition and future development.
• KKR & Singtel – September 2026: KKR and Singtel completed the acquisition of ST Telemedia Global Data Centres, providing the company with additional capital and financial flexibility to accelerate development of AI-ready data-center infrastructure across its international portfolio.
• Yondr Group & Cerberus – August 2026: Yondr Group and Cerberus acquired a 40-acre site in Manassas, Virginia, enabling construction of a 72 MW data-center campus expected to become operational in 2029 and designed to serve hyperscale, cloud and AI customers
Data Center Construction – Whitespace Opportunities
• AI-ready data center retrofits – Upgrading existing facilities for higher rack densities, advanced power distribution, and liquid cooling.
• Water-efficient construction – Developing low-water or water-free cooling infrastructure for projects located in water-stressed regions.
• Grid-integrated data centers – Combining utility power, battery storage, renewable generation, and flexible electrical loads within the campus design.
• Prefabricated MEP systems – Using factory-built electrical rooms, cooling modules, pipe racks, switchgear assemblies, and other MEP components to shorten construction timelines.
• Liquid-cooling-ready buildings – Designing floors, piping routes, CDU spaces, and mechanical systems specifically for high-density AI workloads.
• Battery-storage-ready campuses – Integrating BESS infrastructure into data center construction to support peak-load management and grid flexibility.
• Brownfield data center conversion – Converting existing industrial buildings and other suitable structures into high-density computing facilities.
• Heat-reuse infrastructure – Designing facilities to capture waste heat for nearby industrial, commercial, agricultural, or district-energy applications.
Get 20% complimentary customization within the report: https://www.datamintelligence.com/customize/data-center-construction-market?indhu
Market Segmentation
By Infrastructure
• Electrical Infrastructure – 32%: Holds the largest share as power distribution, switchgear, generators, and related systems are essential for continuous data center operations.
• Mechanical Infrastructure – 27%: Strong demand comes from mechanical systems supporting temperature control, airflow management, and facility reliability.
• Cooling Systems – 18%: Increasing rack densities and computing workloads are driving greater investment in advanced cooling technologies.
• UPS Systems – 10%: Remains critical for power continuity and protection against electrical interruptions.
• Racks – 6%: Demand is supported by expanding server capacity and higher-density deployments.
• General Construction – 5%: Covers structural, civil, and facility-development requirements.
• Others – 2%: Includes supporting infrastructure and specialized construction components.
By Data Center
• Tier 3 – 48%: Dominates as enterprises increasingly require redundant infrastructure and high availability without the cost and complexity of the highest-tier facilities.
• Tier 4 – 28%: Adoption is concentrated among mission-critical facilities requiring maximum redundancy and fault tolerance.
• Tier 2 – 17%: Continues to serve organizations with moderate availability and infrastructure requirements.
• Tier 1 – 7%: Primarily supports smaller facilities with basic infrastructure and limited redundancy.
By Organization Size
• Large Size Organization – 55%: Leads due to extensive investments by hyperscalers, technology companies, financial institutions, and other data-intensive enterprises.
• Medium Size Organization – 29%: Increasingly invests in dedicated and colocation infrastructure to support digital operations and growing workloads.
• Small Size Organization – 16%: Adoption is driven mainly by smaller private facilities, cloud services, and outsourced data center solutions.
Regional Analysis
North America – 38% Share
North America leads the market, supported by extensive hyperscale and colocation development, cloud infrastructure expansion, and sustained investment in high-capacity facilities across the U.S. and Canada.
Asia Pacific – 30% Share
Asia Pacific holds a strong position as cloud adoption, digital services, AI workloads, and data localization requirements continue to encourage new data center construction across major markets such as China, India, Japan, Singapore, and Australia.
Top Key Players
• Schneider Electric
• Turner Construction Company
• DPR Construction
• AECOM
• Mortenson
Company Profiles
Schneider Electric
Schneider Electric provides integrated electrical, power management, cooling and infrastructure technologies for data centers. Its portfolio addresses high-density computing, AI-ready facilities and energy management requirements.
Turner Construction Company
Turner Construction provides construction management and delivery services for mission-critical facilities. Its capabilities cover complex data center projects requiring coordinated electrical, mechanical and building infrastructure.
Unlock Full 360° Strategic Report: http://datamintelligence.com/buy-now-page?report=data-center-construction-market?indhu
Conclusion
Data center construction is entering a phase in which the physical requirements of AI are influencing almost every major design decision. Power availability, cooling architecture, water access and financing structures are now closely connected to where and how new facilities are built.
The projects announced by Meta, Google and Amazon in 2026 illustrate this shift. Gigawatt-scale campuses, built-to-suit facilities, dedicated energy infrastructure, demand-response agreements and water-conscious cooling strategies are becoming part of the development toolkit. These changes are creating new requirements for construction companies, engineering firms, power suppliers and infrastructure technology providers.
FAQs
1. What is the projected CAGR of the Data Center Construction Market?
2. Which region leads the Data Center Construction Market?
3. Which region is expected to grow fastest?
4. What is changing data center construction requirements?
5. How are developers addressing power constraints?
Contact Us:
Sai Kiran
Business Development Manager
DataM Intelligence 4market Research LLP
6th Floor, M2 Tech Hub, Lalitha Nagar, Habsiguda,
Secunderabad, Hyderabad, Telangana 500039
USA: +1 877-441-4866
Email: Sai.k@datamintelligence.com
About Us :
DataM Intelligence is a Market Research and Consulting firm that provides end-to-end business solutions to organizations from Research to Consulting. We, at DataM Intelligence, leverage our top trademark trends, insights and developments to emancipate swift and astute solutions to clients like you. We encompass a multitude of syndicate reports and customized reports with a robust methodology.
Our research database features countless statistics and in-depth analyses across a wide range of 6300+ reports in 40+ domains creating business solutions for more than 200+ companies across 50+ countries; catering to the key business research needs that influence the growth trajectory of our vast clientele.
This release was published on openPR.

